

For startups, one of the biggest questions around AI isn’t just about what the technology can do; it’s what happens to the people doing those jobs when it can do more than them.
That’s been a massive topic of discussion for a number of years, and the question has become far more noteworthy since recent reports that HSBC is planning sweeping cuts across its UK wealth management business as it increases its use of AI.
According to the Financial Times, the bank is considering cutting around half of its management and specialist roles, while the number of financial advisers could fall by as much as 70%. The bank is reportedly currently consulting with staff on the proposed changes.
The question is, beyond the isolated job losses at HSBC, is this indicative of a more general trend, and what does this mean for smaller companies that are building their teams now?
AI May Change the Future of Jobs
The HSBC story might sound like a warning that AI is coming for professional jobs, and while it’s a little bit more complicated than that, it’s a good starting point. Indeed, many experts argue that wealth management is simply an early example of a much broader shift we’re seeing in AI use and employment patterns.
For startups, that means it may be time to start taking the lead on these clear warnings. AI doesn’t necessarily mean taking an existing role, putting an AI system in its place and calling it a day. Instead, founders may increasingly find themselves designing jobs around what humans and AI are each good at from the start. Dorman says the firms that get this right will use AI to take on routine work so people can focus on higher-value responsibilities. “The real shift isn’t fewer people, but people doing different, higher-value work alongside AI,” he adds.
More from News
- Moterra AI Achieves Select Partner Tier In Anthropic’s Claude Partner Network
- GoDaddy Launches Web App Hosting With API For AI Coding Tools
- 7 In 10 Consumers Have Never Investigated What’s Inside Their Smartphone
- Tango Turns Live Communities Into a Force For Breast Cancer Research
- Two Thirds of Brits Are Telling AI Chatbots Their Secrets But Don’t Trust The Companies Behind Them
- Video Game Companies Are Abandoning “Buy Our Console To Play This” – Here’s Why
- UK Gambling Operators Face New Deposit Limit Rules From 30 September
- How A Ransomware Gang Hijacked A Rival Gang’s Website – And Is Now Extorting Them For “2.333% Of Their Net Worth
Some Jobs Will Be More Vulnerable Than Others
Hasan Hassoun, Head of Growth and AI at ThePayStubs, sees a similar pattern: “A cut that size says more about what those adviser jobs contained than about AI outthinking advisers,” he says. “Strip out the assembly work, pulling statements, reconciling positions, building the review pack before anyone forms a view, and plenty of white-collar roles get noticeably smaller.”
That could be particularly relevant to startups, where teams are often small enough that one person may be responsible for a huge amount of administrative and information-heavy work. If AI could be used to do all that, why wouldn’t it be?
Hassoun believes professional services could face similar pressure, particularly where employees spend much of their time retrieving, organising and processing information. “The roles that were mostly lookup will shrink hard, though,” he says.
For a startup deciding who to hire next, this begs the question: does the business really need another person to gather and organise information, or does it need someone who can interpret it, make decisions and take responsibility for the outcome once an AI model has done the tedious work?
Human Accountability Still Matters More Than Ever
That doesn’t mean human expertise suddenly becomes irrelevant; in fact, in many ways, quite the opposite. Shawn Rea, Fractional CFO and Co-Founder of Exit CFO, says AI can already handle much of the routine work that’s involved in advisory roles, including gathering information, filling in forms, rebalancing portfolios and writing reports.
However, there’s one thing AI can’t instantly take away, and that’s responsibility and accountability. As Rea puts it, “What it can’t do is take responsibility. If a client’s pension goes the wrong way, they want a person who made the call and can explain it.” And understandably so, I’d say. Rea expects to see fewer advisers but more senior professionals who spend their time reviewing AI-generated work and standing behind the advice.
I think it’s safe to say that that principle could apply well beyond wealth management. For startups, the valuable employee of the future may not necessarily be the person who can produce the most work, but rather the one who is capable of judging whether that work is being done properly.
Some Startups Are Already Testing The Model
Now, this isn’t exactly hot news; some strtups are already operating based on this model. Evgenii Arsentev, PhD, CEO of AskDocDoc, says his company uses AI agents across areas including CRM and its hiring funnel: “If a test can check the result, an agent gets it. If the other person has to trust you, a human does it,” he says. And perhaps that’s one of the more useful (and luckily, most simple) lessons from the HSBC story.
Arsentev says AskDocDoc tested an AI voice agent for around a month, but ultimately kept its phone interactions human because people didn’t want to talk to a robot. “I think in wealth advice, the calculation and paperwork will go to software, and the trust part will stay with humans,” he says.
For startups, then, HSBC’s AI-driven cuts may be less about asking whether AI will replace employees and more about asking what employees should actually be spending their time doing. Ultimately, if AI can handle the repetitive work, perhaps the smartest teams won’t simply hire fewer people; they’ll hire people whose value comes from judgement, accountability, trust and the ability to work effectively alongside the machines doing the grunt work, so to speak.
The Experts Weigh In:
- Hasan Hassoun: Head of Growth and AI at ThePayStubs
- Shawn Rea: Fractional CFO and Co-Founder, Exit CFO
- Evgenii Arsentev, PhD: Chief Executive Officer at AskDocDoc
- Pavlo Kharmanskyi: Founder of OnlyMonster
- Jeff Phipps: General Manager Northern Europe at ADP
Hasan Hassoun, Head of Growth and AI, ThePayStubs
“A cut that size says more about what those adviser jobs contained than about AI outthinking advisers. Strip out the assembly work, pulling statements, reconciling positions, building the review pack before anyone forms a view, and plenty of white-collar roles get noticeably smaller. Wealth management is exposed because so much of it ran on retrieval. Professional services will feel the same pressure.
“What AI does not take is the part where a client is frightened about their own retirement and wants a person accountable for the advice. We run AI across the document and data side of ThePayStubs, and the pattern holds: the machine assembles, a person still decides. So I would expect responsibilities to be rewritten rather than skilled professionals removed altogether. The roles that were mostly lookup will shrink hard, though. Advisers who spent their week acting as a human search engine have the most to worry about.”
Shawn Rea, Fractional CFO and Co-Founder, Exit CFO
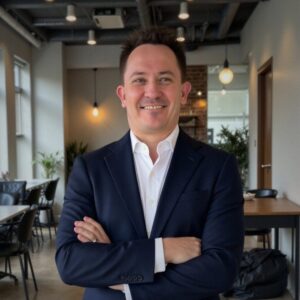
“I’m not surprised. A lot of what an adviser does day to day is gathering information, filling in forms, rebalancing portfolios and writing up suitability reports. AI can already do most of that, and quicker. We use it for exactly that kind of work in our own firm.
“What it can’t do is take responsibility. If a client’s pension goes the wrong way, they want a person who made the call and can explain it. That part of the job isn’t going anywhere.
“So I’d expect fewer advisers, but more senior ones, spending their time checking the work and standing behind the advice rather than producing it. Accountancy is heading the same way.”
Evgenii Arsentev, PhD, Chief Executive Officer at AskDocDoc
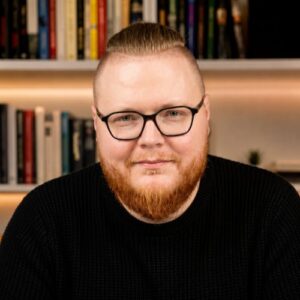
“I’m a medical doctor by education and CEO of AskDocDoc (telehealth). Not a banker, so I answer from my own small company, which runs on AI agents.
“We’re a startup and could never afford in-house development or HR. Agents made that possible for us, including our CRM and the hiring funnel.
“If a test can check the result, an agent gets it. If the other person has to trust you, a human does it. We tried an AI voice agent for about a month, but people didn’t want to talk to a robot, so the phones are still done by people.
“I think in wealth advice the calculation and paperwork will go to software, and the trust part will stay with humans.”
Pavlo Kharmanskyi, Founder of OnlyMonster
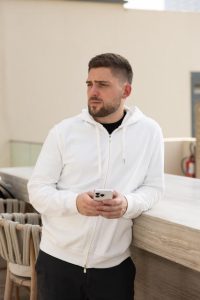
“I appreciate the irony of someone who has spent 20 years building products that automate other people’s jobs now arguing that we should keep humans involved. But I genuinely believe the biggest opportunity with AI is making people better at working with machines, rather than seeing how many people we can replace. I use AI coding agents every day. They allow me to build things at a speed I wouldn’t have believed possible even two years ago. I’m still coming up with the ideas, testing them, making mistakes and occasionally wondering what on earth the computer has just done.
“I see the same thing across the teams I work with. Someone who understands how to use AI can now achieve several times what they could previously. Equally, an experienced employee who refuses to embrace it can quickly find themselves falling behind. That’s a problem, but one I’d much rather solve through education than redundancy. I’d love to see companies put as much effort into teaching their employees to work with AI as they put into calculating how much money they could save by replacing them. In my experience, making a good employee considerably more productive is often a far better investment than getting rid of them.”
Jeff Phipps, General Manager Northern Europe at ADP
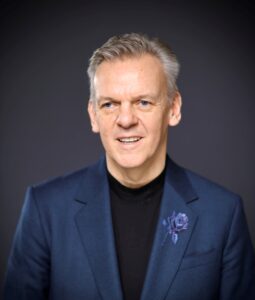
“AI is starting to reshape professions rather than replace them and it is already affecting entry-level positions in particular. The US, often a bellwether for the UK and European workforces, is showing early signs of this. Stanford Digital Economy Lab’s “Canaries dashboard”, in collaboration with ADP Research, shows employment falling among early-career workers in the most AI-exposed jobs, while growing in less exposed, hands-on roles. It suggests that AI is not eliminating jobs at scale, but is instead changing how work gets done, with the impact so far appearing more at the task level than at the job level.
“I expect the impact to vary significantly across industries and business models, depending in part on the quality, quantity and availability of data. And as routine and entry-level work becomes increasingly automated, organisations will need to think carefully about how they develop the expertise, judgement and empathy that have traditionally been built through early-career roles. Understanding and navigating these shifts will require greater visibility into how work and workforce needs are evolving. For business leaders, having the right data and a connected view across payroll, HR and workforce management will therefore be critical to making better decisions on hiring, workforce structure and technology investment.”